Measured in Pounds, the Cost of Living Went Up. Measured in Gold, It Fell by Roughly 85%.


We all know the story.
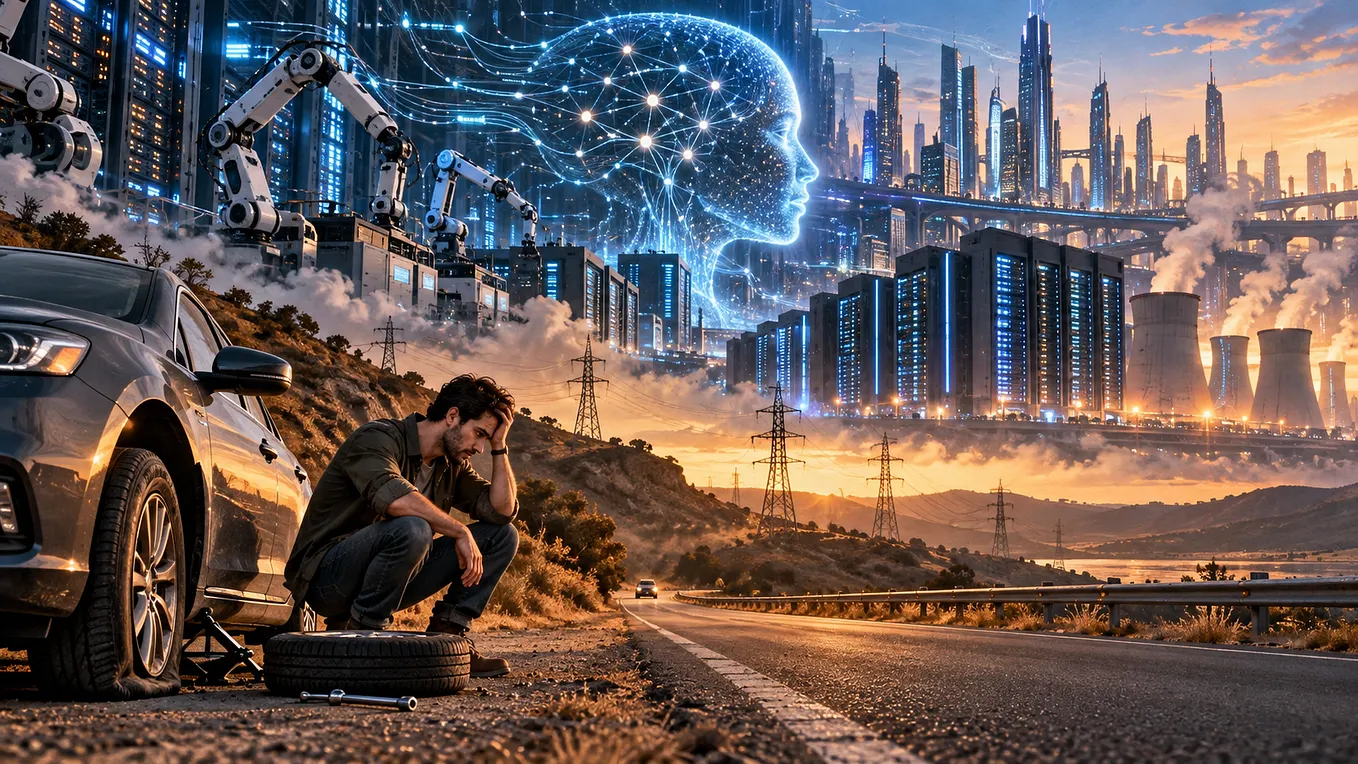
The cost of living is going up.
Food is more expensive. Energy is more expensive. Houses are more expensive. Insurance is more expensive. Almost everything seems to cost more than it did a few years ago.
Meanwhile, salaries do not seem to be keeping up.
The result is something many people can feel without needing an economist to explain it: despite earning more pounds than before, we do not necessarily feel richer.
In fact, many of us feel the opposite.
We feel squeezed.
Now imagine I told you something completely different:
The cost of living has actually been falling.
You might reasonably ask:
Are you crazy?
So let me explain.
Remove the pound from the equation
For a moment, imagine that the pound does not exist.
Neither does the dollar.
Forget euros, yen and every other fiat currency.
We still need some way of measuring value, so let us use something humans have used as money and a store of value for thousands of years:
gold.
Instead of asking how many pounds an average household needs each month, ask a different question:
How many grams of gold does an average household need each month?
Suddenly, the picture changes dramatically.
Around the beginning of this century, our estimate suggests that maintaining the consumption of an average UK household required roughly 250–280 grams of gold per month.
By 2025, depending on the precise household-expenditure measure used, that figure had fallen to approximately 35–40 grams.
Think about that for a moment.
Measured in pounds, household expenditure rose enormously.
Measured in gold, it fell by roughly 85%.
Same household.
Same country.
Same basic concept of food, transport, energy, entertainment and everyday living.
But a completely different answer depending on the ruler we use.
What if the ruler itself is changing?
Imagine you want to measure how quickly your child is growing.
Every month, you stand your child beside a measuring pole.
The child seems to be getting taller and taller.
So naturally you conclude:
“My child is growing very quickly.”
But there is a problem.
Unknown to you, the measuring pole itself is getting shorter every month.
Suddenly, your measurements become much harder to interpret.
That is the question I think we should ask about money.
We assume that £1 today is the same measuring unit as £1 twenty years ago.
Numerically, of course, it is.
Economically, it isn’t.
The purchasing power of money changes.
So when a house rises from £100,000 to £300,000, or the weekly household budget rises from £400 to £700, we instinctively conclude that the underlying thing has become dramatically more expensive.
Sometimes it has.
But another part of the change can come from the measuring unit itself losing purchasing power.
The ruler is moving.
Try measuring with gold instead
Gold gives us an interesting alternative ruler because its supply behaves very differently from fiat currency.
Governments and central banks can create additional currency and banking-system liquidity. Credit can expand. Government debt can rise. Monetary systems can accommodate vastly larger nominal quantities of money over time.
Gold cannot be created in the same way.
More gold can certainly be mined, but its supply grows slowly and extracting additional gold requires real resources, capital and time.
That does not make gold perfectly stable.
Far from it.
Get Tusharkoley’s stories in your inbox
Join Medium for free to get updates from this writer.
Gold can rise sharply, fall sharply and spend years moving sideways. Anyone looking at the 1980s and 1990s can see that clearly.
But over approximately the last quarter-century, something remarkable has happened.
The amount of gold required to finance an average British household’s consumption has collapsed.
In other words, gold’s purchasing power relative to that household basket has increased enormously.
And that leads to a very different interpretation of the famous chart showing gold reaching record highs.
We normally look at gold rising from hundreds of pounds an ounce to thousands of pounds an ounce and say:
“Gold has become incredibly expensive.”
But perhaps there is another way to look at the same chart.
Maybe gold has not changed nearly as much as the currency in which we are measuring it.
The strange illusion of becoming richer
This may also help explain something that otherwise feels contradictory.
Most people’s nominal salaries have increased over the decades.
Someone who earned £20,000 many years ago might earn £35,000 or £40,000 today.
On paper, that person is earning much more money.
Yet they may not feel dramatically wealthier.
Housing consumes more of their income. Everyday expenses feel heavier. Saving for assets can feel increasingly difficult.
The salary number became larger.
But so did almost every other number around it.
Perhaps nominal pounds are telling us less than we think.
Instead of asking:
“How many pounds do I earn?”
we could occasionally ask:
“How much real purchasing power does my labour earn?”
Gold is not the only possible benchmark for answering that question. We could use houses, energy, commodities or a basket of goods.
But gold gives us a particularly fascinating long-term reference point.
The graph that changed how I looked at inflation
When I first looked at household expenditure expressed in grams of gold rather than pounds, I expected it to be lower.
I did not expect the difference to be this dramatic.
Around 2000, the estimated monthly household requirement was approximately 270 grams of gold.
By 2025 it was roughly 35–40 grams.
There were reversals along the way. The decline was not smooth. Gold had periods of weakness, and household costs continued changing.
But stand far enough away from the graph and the direction over the last two decades is difficult to miss.
The number of pounds required to run a household went up.
The number of grams of gold required went dramatically down.
Both statements are true simultaneously.
That is what makes this comparison so interesting.
So which price is the real price?
There probably isn’t one perfect answer.
Gold itself fluctuates.
Household consumption changes over time.
The average family today buys things that barely existed thirty years ago.
And modern economies clearly cannot be reduced to a single commodity-price relationship.
But the exercise exposes something important:
Prices never exist in isolation.
A price is always a ratio.
When we say something costs £100, what we are really saying is that the object can currently be exchanged for 100 units of sterling.
If the value of sterling changes, the price changes even if part of the underlying economic reality has not.
That is why changing the denominator can completely change the story.
And perhaps we have become so accustomed to measuring everything in pounds and dollars that we have forgotten to question the measuring stick itself.
Maybe gold isn’t becoming expensive
When gold reaches another record high, the headline usually says:
Gold hits record price.
But after looking at household expenses this way, I find myself asking a different question.
What if we have the relationship backwards?
What if gold isn’t becoming extraordinarily expensive?
What if our money is becoming extraordinarily cheap?
Perhaps the next time we complain that everything is getting more expensive, we should ask one more question:
Expensive compared with what?